Dead Reckoning: What the 4% Rule Cannot See

Dead Reckoning: What the 4% Rule Cannot See

Most retirement planning math is correct. The problem is the question it's answering.

The 4% rule was built for a 30-year retirement. An early retiree who leaves work at 35 and lives to 90 needs a portfolio that lasts 60 years — and the gap between what the rule promises and what that horizon requires is fifteen thousand dollars per year on a million-dollar portfolio. The formula is right. The voyage is twice as long.

In this episode:

  • The three-number problem: William Bengen revised his own rule upward to 4.7% after extending his model beyond the original stock-bond mix. Morningstar's December 2025 forward-looking analysis sets the 30-year base case at 3.9% — and finds that higher equity allocations do not support higher withdrawal rates, because the volatility works against you. Extended-horizon researchers place 50- to 60-year safe starting rates in the low-3% range. Three figures, three different questions. Understanding which one applies to your situation is the whole ballgame.
  • Why 1966 was the worst year to retire in recorded US history — worse than 1929, worse than 2008 — over a 30-year horizon. Bengen's SAFEMAX for that cohort was 4.15%: a withdrawal rate meaningfully above 4.1% would have depleted the portfolio. Not because of a crash. Markets peaked and ground sideways for years as inflation climbed from 3% to 12%. No sudden crisis. Just a slow, compounding mismatch between what the portfolio returned and what inflation required. 90% of all historical failures cluster in that single decade — and the conditions that produced it have a more than passing resemblance to May 2026.
  • Healthcare is not a line item. Fidelity's 2025 estimate: $172,500 in lifetime after-tax healthcare costs for a single 65-year-old with Medicare. An early retiree has no Medicare until 65. The enhanced ACA credits that bridged that gap expired January 1, 2026. Above roughly $62,600 of MAGI — based on 2025 federal poverty guidelines — the restored subsidy cliff can eliminate thousands in annual premium assistance overnight. In many markets, unsubsidized early retirees in their early 60s face four-figure monthly premiums before a single claim is filed.
  • The guardrails alternative and Social Security. Morningstar's 2025 research found a specific guardrails configuration supported a 5.2% starting rate on a 40/60 portfolio versus 3.9% for fixed withdrawals — but with spending variability as the price. For an early retiree with no Social Security income for 25 years, and zeros filling the 35-year benefit formula that determines the eventual benefit, that guaranteed income floor may not exist when it is needed most.
  • FIRE is a spectrum. Barista FIRE pairs a mid-size portfolio with a part-time job that provides employer health coverage — solving the pre-Medicare problem structurally rather than hoping the ACA holds. Coast FIRE requires only enough invested early enough that compound growth carries the rest: at 5% real, a 35-year-old targeting $1.5M needs roughly $347,000 today. The real value of financial independence is not the day you stop working. It is what it does to your negotiating position long before then.

Read the written version — with the full data, withdrawal rate breakdowns, and card layouts — at quietvelocity1.substack.com, the companion Substack to Conviction Bet.

New episodes weekly. Subscribe on Apple Podcasts, Spotify, YouTube, or Amazon Music.

Conviction Bet is independent investment commentary. Nothing in this episode is investment advice.

Tämä jakso on lisätty Podme-palveluun avoimen RSS-syötteen kautta eikä se ole Podmen omaa tuotantoa. Siksi jakso saattaa sisältää mainontaa.

Jaksot(21)

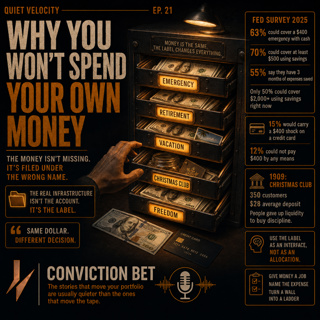
Why You Won't Spend Your Own Money

Why You Won't Spend Your Own Money

Your balance tells you what you have. The label shapes what you'll actually use. And you're the one who wrote it.The Federal Reserve asked Americans two versions of the same question. 70% said they co...

25 Elo 32min
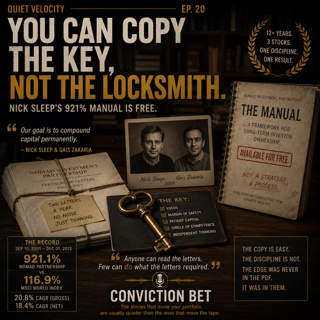
You Can Copy The Key, Not The Locksmith: Nick Sleep's 921% Manual Is Free

You Can Copy The Key, Not The Locksmith: Nick Sleep's 921% Manual Is Free

Two men, no analysts, no leverage, two letters a year. Twelve and a quarter years later: 921.1% against 116.9% for the MSCI World. A dollar became $10.21. Then they closed the fund, handed the capital...

13 Elo 37min
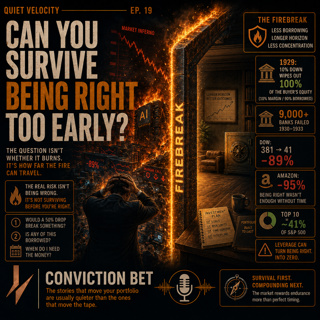
Can You Survive Being Right Too Early?

Can You Survive Being Right Too Early?

In late July, the market decided the AI build-out had gone too far. The Nasdaq fell into its second correction of the year, the Philadelphia Semiconductor Index dropped into a technical bear market, a...

6 Elo 32min
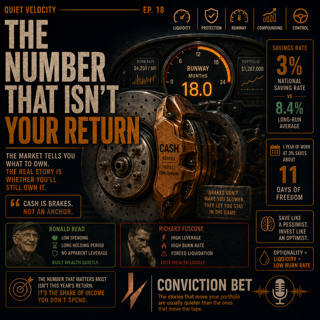
The Number That Isn't Your Return

The Number That Isn't Your Return

A Vermont gas station attendant died in 2014 holding $8 million and a five-inch stack of stock certificates. That same year, a former Merrill Lynch executive who once ran the firm's Latin America arm ...

30 Heinä 39min
He Knew Better. He Did It Anyway

He Knew Better. He Did It Anyway

In March 2000, Stanley Druckenmiller had the internet bubble exactly right. He had shorted it, written the thesis, and run money for two decades without a losing year. Then he watched two junior trade...

23 Heinä 33min
Deferred Maintenance: Cash, Muscle, Sleep

Deferred Maintenance: Cash, Muscle, Sleep

The four biggest tech companies are planning as much as $725 billion of capital spending this year — up 77% in a single year — much of it on machines that never have to sleep. The people underwriting ...

16 Heinä 39min
The Rulebook You Never Read

The Rulebook You Never Read

At Monday's close, funds tracking the Nasdaq-100 lined up to buy an estimated $4 billion of SpaceX stock. Nobody at those funds decided SpaceX was worth owning — a rulebook decided. And three weeks ea...

9 Heinä 32min
The Four Cards You're Not Playing

The Four Cards You're Not Playing

79% of professional large-cap fund managers lost to the S&P 500 last year. Stretch the window to fifteen years and the failure rate hits roughly 90%. The internet's favorite conclusion: if the pros ca...

1 Heinä 28min
Suosittua kategoriassa Liike-elämä ja talous

sijotuskasti
vallattomat
psykopodiaa-podcast
rss-rahapodi
mimmit-sijoittaa
rss-oivalluksia-rahasta-elamasta
ostan-asuntoja-podcast
lakicast
oppimisen-psykologia
rss-inderes
rss-paasipodi
juristipodi
hyva-paha-johtaminen
rss-karon-grilli
rss-rahamania
rss-pinnan-alle
rss-alanvaihtajat
rss-startup-ministerio
rahapuhetta
rss-siksi-viestinta